Private equity firm Permira has agreed to acquire a majority stake in Flint Group, the Kansas City, Missouri residential HVAC, plumbing, and electrical services platform, from General Atlantic, the firms told Reuters on November 5. The deal is valued at more than $1.5 billion, according to people familiar with the matter cited by Reuters. The parties expect it to close by the end of 2026.
The asset.
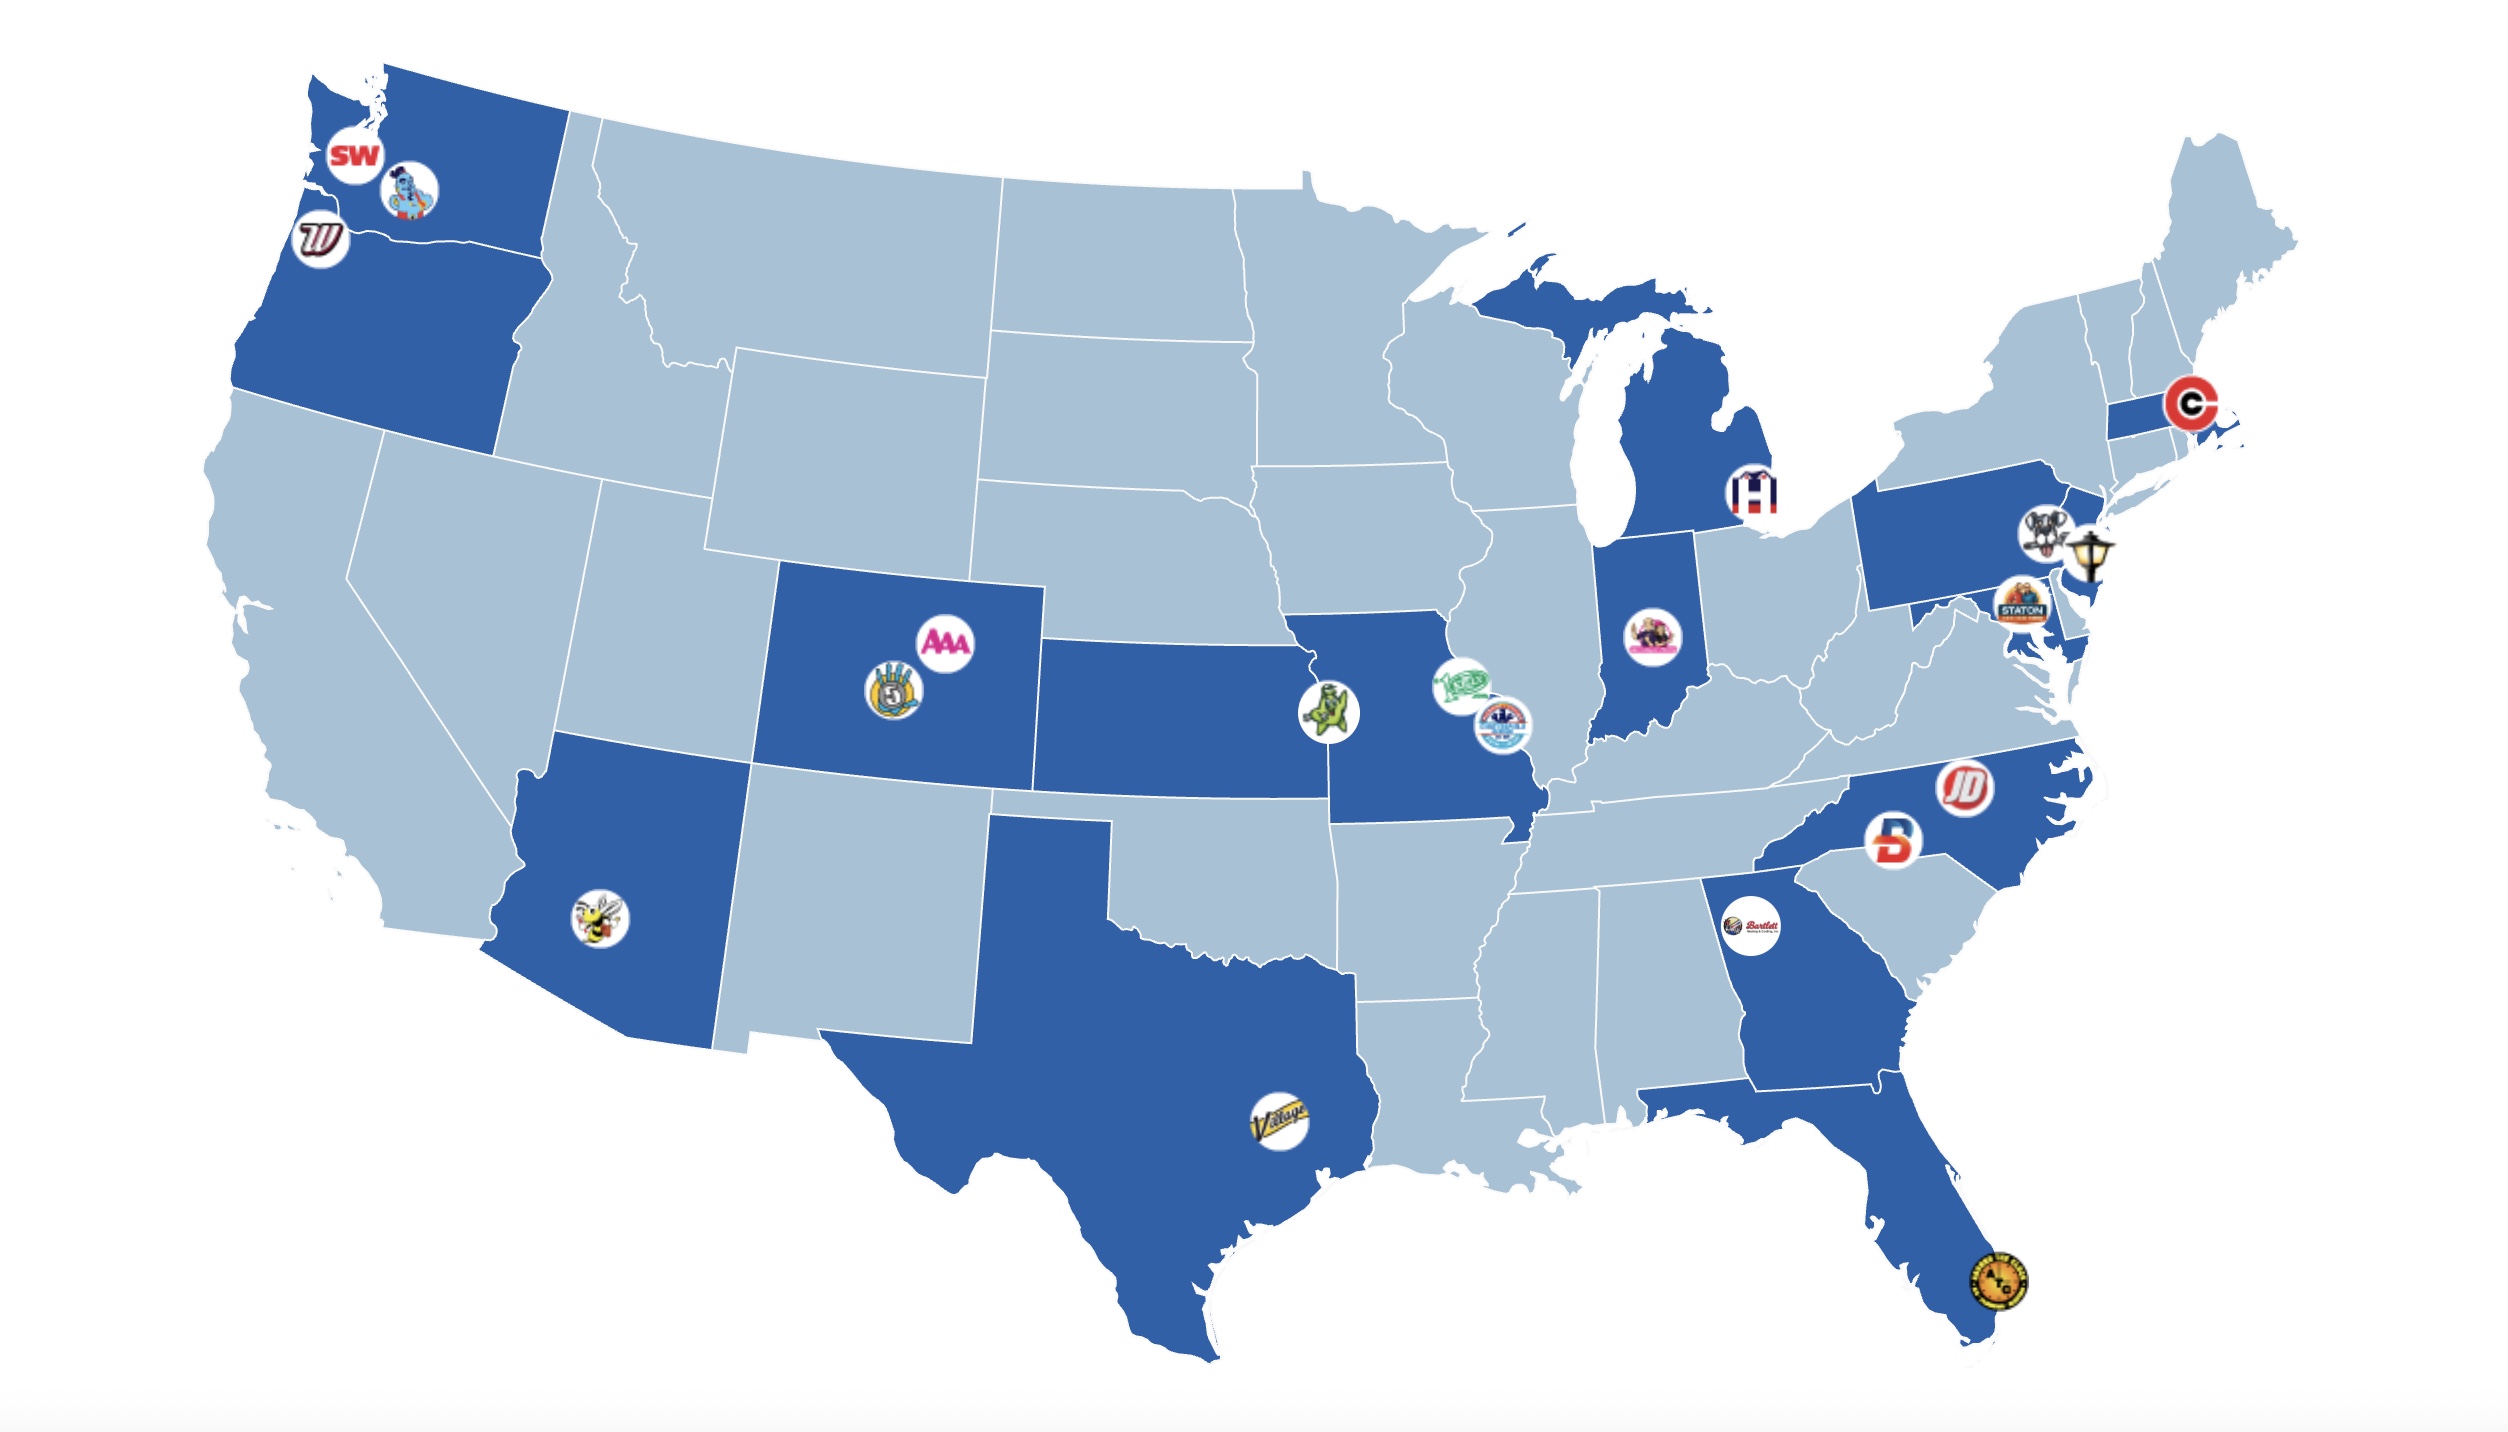
Flint Group was founded in 2019 by industry veterans Trevor Flannigan and Collin Hathaway. It operates and partners with regional residential service brands that keep their local names, and it covers HVAC, plumbing, and electrical. Its 2026 add-ons have included Staton Heating, Cooling & Plumbing in Annapolis, Jake’s Heating, Air & Plumbing in Indianapolis, and Air Around the Clock in South Florida.
Homepros, citing Ingram’s, has reported that Flint generated more than $400 million of revenue in 2025, more than three times its 2022 level. The company has not disclosed EBITDA, and neither Permira nor General Atlantic disclosed financial terms.
The buyer.
Permira is a global private equity firm. Its partner and co-head of consumer, David Erlong, said in a statement viewed by Reuters that the firm plans to bring “Permira’s experience of backing and scaling leading consumer platforms, alongside our deep digital expertise,” to accelerate Flint’s growth. That framing matters: Permira is underwriting Flint as a consumer brand business with a digital customer-acquisition angle, not as a construction or mechanical contractor.
A sponsor-to-sponsor handoff, on schedule.
The structural point is how fast this went from rumor to signed deal. Our September Insights coverage put Flint’s sale process in market when it was still in its early stages. Roughly eight weeks later, a large-cap buyer has agreed to terms, with a close targeted inside the calendar year.
It is also a clean example of the second leg of a residential platform’s life. General Atlantic invested in 2023 when Flint was a seven-brand regional network. Three years and thirteen brands later, it is selling majority control to a larger sponsor. Every owner who partnered with Flint during that stretch, and rolled equity into the platform, now has a mark on that equity set by this transaction. The terms of that roll — how much was rolled, at what entry value, and whether it sells down now or rolls again — are where a founder’s second payday is decided.
The M&A environment: PE keeps paying up for residential multi-trade.
Flint is not an outlier. It is the latest platform-level capital event in a residential HVAC, plumbing, and electrical tape that has stayed loud all year — and the common thread is private equity’s continued willingness to underwrite multi-brand home-services networks at scale.
Earlier in 2026, Blackstone agreed to acquire Champions Group from Odyssey Investment Partners for approximately $2.5 billion, putting a large-cap perpetual-capital flag on a membership-model residential services platform and giving the category one of its clearest institutional comps. Apollo’s minority investment in Apex Service Partners, at a reported $10 billion valuation including debt, then priced the ceiling even higher — a minority check that left Alpine in the seat while confirming how much capital wants into the same residential multi-trade thesis. In October, GHK Capital completed its acquisition of USA Hometown Experts, closing the Southeast platform sale that had been in market earlier in the year and putting a newly capitalized buyer back into add-on mode across Alabama, Georgia, Tennessee, Florida, and neighboring states.
Flint’s September sale process sat in that same calendar: a General Atlantic–backed platform that had scaled from seven brands in five states to a national footprint, testing an exit while other sponsors were still in extended holds. Eight weeks later, the process has a signed majority buyer. That cadence — rumor, process, sponsor-to-sponsor handoff inside a calendar year — is what owners should expect more of as platforms that raised capital in 2020–2023 reach the natural end of a first hold.
Several other sponsor-backed residential HVAC, plumbing, and electrical platforms remain in extended hold periods. More of them are expected to test the market into 2027. The buyer set that has already shown up — Blackstone, Apollo, GHK, and now Permira — is not a one-off cohort. It is large-cap and upper-mid-market capital treating residential multi-trade as a durable consumer platform category, not a niche contractor niche.
What it means.
For owners of residential HVAC, plumbing, and electrical businesses, large-cap buyers are still paying up for platforms built from regional brands, and that demand flows down to the add-on market. A platform with a fresh owner and new capital typically resumes acquisitions quickly. A platform in the middle of a sale process often pauses them.
If you are talking to a platform today, it is worth knowing where its sponsor sits in its hold. It is also worth understanding what happens to rolled equity at the next sale. Those two facts shape what a “partnership” is actually worth to you.
Earlier coverage: Schryver & Co. Insights, September 9, 2026. No official Permira or Flint Group press release was available at publish time.
Own a residential HVAC, plumbing, or electrical business?
Schryver & Co. advises trades owners with roughly $5 million to $100 million of revenue and $1 million to $5 million or more of EBITDA, depending on the vertical. If you want an honest read on what your business is worth, and which platforms would actually compete for it, we are glad to talk. No pitch, no pressure. Reach Will at will@schryverco.com.
Talk with Will →