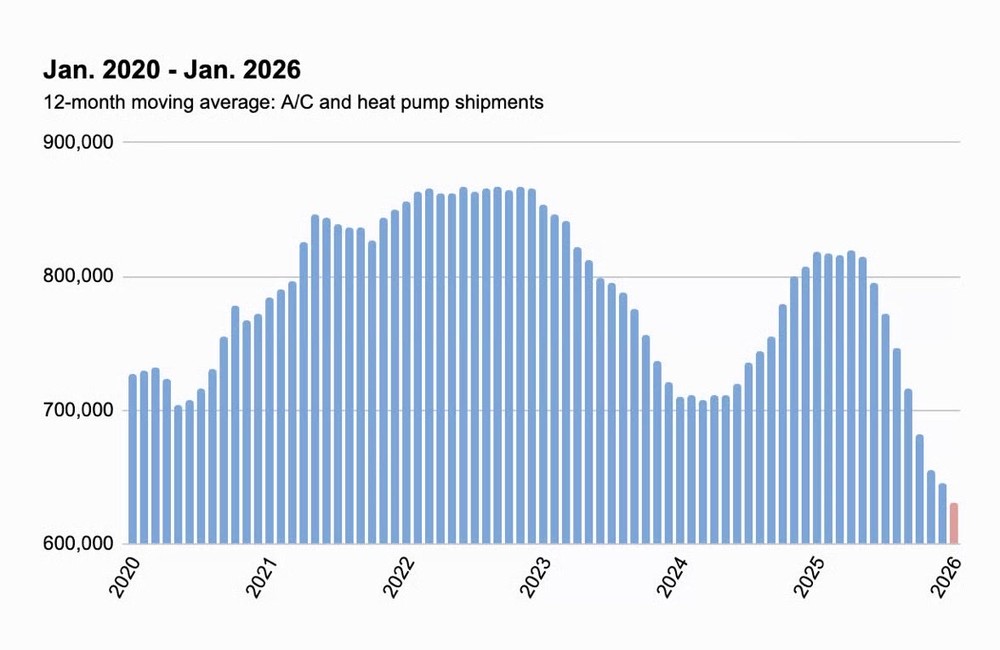
Combined central A/C and heat pump shipments came in at 440,819 units in January, per AHRI data released March 13, as reported by Homepros.news. That's a 29% year-over-year decline — and the eighth consecutive month of 20%+ declines in combined shipments. A/C shipments alone fell 39% YoY; heat pumps were down 16.5%. Full-year 2025 closed down 20% versus 2024.
Unit volume peaked in 2022.
The longer-arc picture is unambiguous. The 12-month moving average peaked at around 870K combined units in late 2022, declined through mid-2024, recovered to ~820K through 2025, and has now rolled back over into 2026. Current pace is back near the post-Great Financial Crisis baseline.
But there's a lot of noise in the comparison.
Most of the headline decline is being measured against an artificially elevated 2024 base. Distributors and contractors stocked up heavily ahead of the January 1, 2025 cutoff for manufacturing R-410A systems — October and November 2024 shipments were up 53% and 55% year-over-year, respectively. That pull-forward is the primary driver behind the 20%+ declines that have rolled through 2025 and into early 2026.
So: yes, demand is softer than it was at the 2022 peak. But "down 29%" is doing a lot of work that's about timing and inventory rebalancing — not demand collapse.
Watching the data and wondering what it means for your business?
We work with operators across residential HVAC, plumbing, electrical, and adjacent service categories. No pitch — just an honest conversation about where you are and what the market is telling you.
Get in Touch →