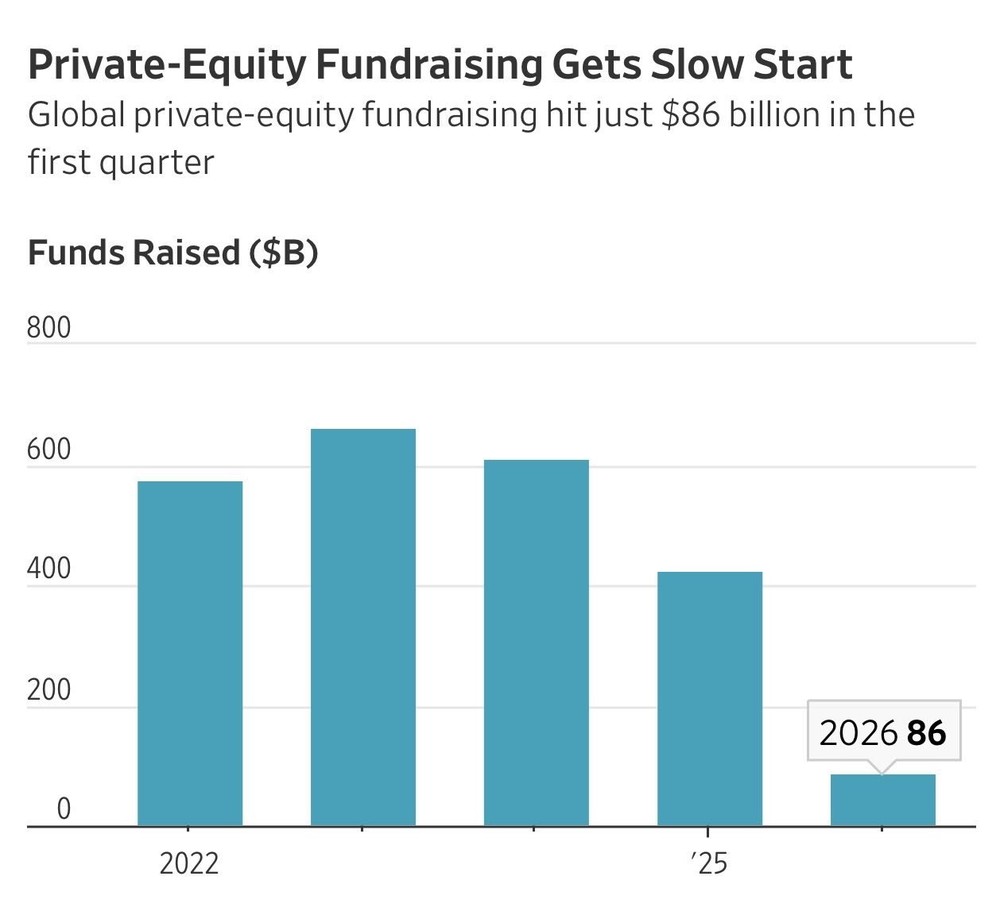
Global private equity fundraising came in at $86 billion in Q1 2026, per Wall Street Journal reporting. At this pace, full-year 2026 is on track to be the industry's worst fundraising year in a decade. The hangover from the frothy 2020–22 investment vintages — when sponsors deployed at peak multiples on inflated EBITDA — is still working its way through the system.
The largest names are still clearing capital.
The headline number masks an important divergence: the biggest names continue to raise. KKR closed on $23 billion, Blackstone added $6.3 billion, and Greenbriar pulled in $5.4 billion. Combined, those three alone account for roughly 40% of the entire quarter's fundraising total.
Why this matters for service businesses.
The same bifurcation showing up in the LP fundraising data is showing up on the deal side. The large-cap firms still raising at scale are exactly the names showing up in residential service M&A — Blackstone on Champions at 18.5x, Goldman on Sila, Carlyle still active in the space. Middle-market sponsors that piled in at peak multiples in 2021–22 are in a much tighter spot today.
The takeaway for operators: the buyer universe for residential and commercial service platforms is consolidating around fewer, larger names. Different buyers, different processes, different multiples than a few years ago.
Watching the market and wondering what it means for your business?
We work with operators across residential and commercial service businesses. No pitch — just an honest conversation about where you are and what the market is telling you.
Get in Touch →