Private equity has spent the last decade rolling up commercial mechanical, electrical, and plumbing (MEP) specialty contractors. The traditional playbook: buy regional independents at 4x–6x EBITDA, integrate operations, build a regional MEP platform, and exit at 9x–11x to the next sponsor or a strategic. Same structure as home services — different entry and exit multiples.
That's been the model. The market just gave it a new option.
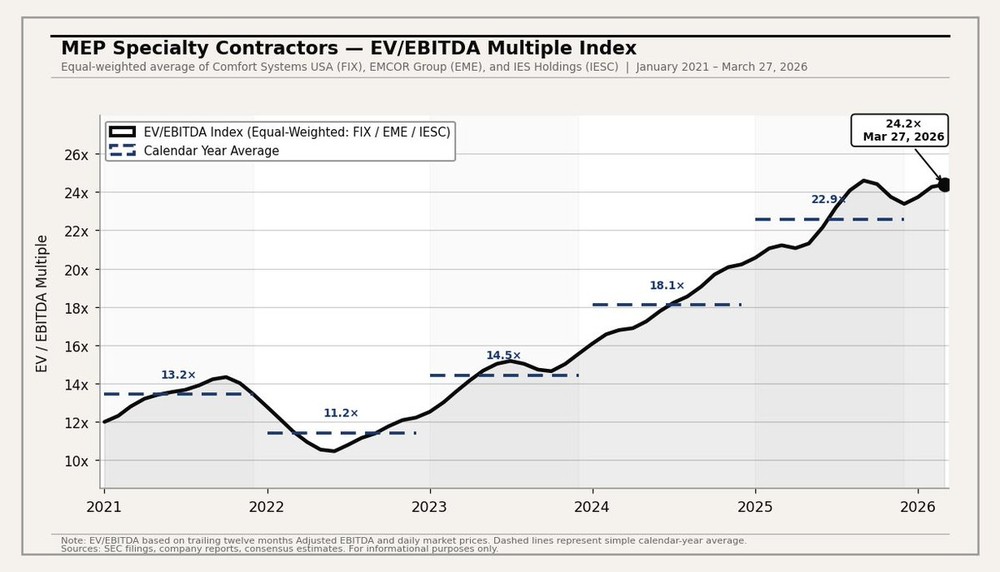
Public comps have run.
The equal-weighted EV/EBITDA multiple for the major MEP publics — Comfort Systems USA, EMCOR Group, and IES Holdings — has climbed from a 2021 calendar-year average of 13.2x to 22.9x in 2025, and sits at 24.2x as of late March. The primary driver: data center exposure. Hyperscaler capex is filling MEP order books with multi-year, high-margin work, and the public markets are paying up for it.
The IPO exit comes into focus.
If public comps hold in the 20x+ range, an MEP platform with the right scale and the right earnings mix has a path to a public-market exit at 15x+ — meaningfully above the 9x–11x historical PE-to-PE exit comp. That's a different IRR story for sponsor and LPs alike. We're hearing more PE-backed MEP platforms actively considering an IPO path that wasn't really on the table 18 months ago.
The open question.
Public-comp multiples here are tied to data center demand. If the hyperscaler buildout continues, 20x+ holds. If it doesn't, the IPO window closes quickly. The platforms being built right now are betting on the former.
So: do these multiples hold long enough for the platforms in market today to walk that path?
Building, running, or evaluating an MEP platform?
We work with operators across commercial mechanical, electrical, and plumbing services. No pitch — just an honest conversation about where you are and what the market is telling you.
Get in Touch →